
PLAN NUMBERS
Plan numbers: use consistent assumptions to compare payment and total cost
A HK$2.4 million principal at an assumed fixed 3.5% annual rate illustrates the monthly-payment and total-interest difference between 20 and 25 years.
Who this direction is for
For owners asking why a lower monthly payment can coincide with higher total interest. Every figure is an educational example, not a lender quotation, real case or achievable result.
Scope of the initial review
The example fixes principal at HK$2,400,000 and assumes a 3.5% annual rate with equal monthly principal-and-interest payments. At 20 years, the payment is about HK$13,919 and total interest about HK$940,568. At 25 years, the payment is about HK$12,015 and total interest about HK$1,204,490. Adding five years lowers the example payment by about HK$1,904 while increasing total interest by about HK$263,922. Fees, incentives, penalty clauses and rate changes are excluded.
Three-number comparison
20-year example
Monthly payment HK$13,919
Total interest HK$940,568
25-year example
Monthly payment HK$12,015
Total interest HK$1,204,490
Term difference
Payment lower by HK$1,904
Total interest higher by HK$263,922
Teaching assumptions: HK$2,400,000 principal, fixed 3.5% annual rate and equal monthly principal-and-interest payments. Fees, incentives, penalties and rate changes are excluded. This is not a lender quotation.
Change one condition at a time
Keep principal, rate and repayment method unchanged when comparing terms. This isolates the effect of term on monthly payment and total interest. The page calculates the 20-year and 25-year examples from the same formula. Display values are rounded only after the underlying calculation.
A simple break-even is only a filter
If a one-off cost is HK$12,000 and the monthly difference is HK$500, the simple calculation is 12,000 ÷ 500 = 24 months. It assumes the same principal and term and excludes time value of money, other fees, penalties, rate changes and the actual holding period. It cannot establish that an option is truly cheaper or better.
Move from an example to a real comparison
Replace the example with the latest balance, remaining term and written terms, then add one-off costs, incentive conditions and rate scenarios for every candidate. The initial output only organises comparison fields and questions. The relevant institution provides the real quotation, valuation and decision.
Common questions
Are these monthly payments current market quotations?
No. The 3.5% rate is a fixed teaching assumption used to show the relationship between term and total interest. Actual rates, costs, incentives and terms come from formal written information.
Why can total payments differ from rounded payment multiplied by the number of months?
Total payments use the unrounded monthly result and are rounded at the end, avoiding the accumulation of a display-rounding difference.
Does a 24-month break-even mean the option becomes better after that date?
No. The simple calculation includes only a one-off cost and monthly difference. It omits other costs, rate changes, time value of money and the actual holding period.
Official sources and further reading
- Hong Kong Monetary Authority: FAQs on mortgages and repayment ability
- HSBC Hong Kong: Home Loan Key Facts Statement
This content is general information for initial organisation only. Eligibility, valuation, approval, fees and terms are determined by current formal information from the relevant institutions.
Six number and planning posters
Open any 4:5 poster in a new tab to zoom. Current poster artwork is in Traditional Chinese; the captions and planning-page links below each poster remain in English.
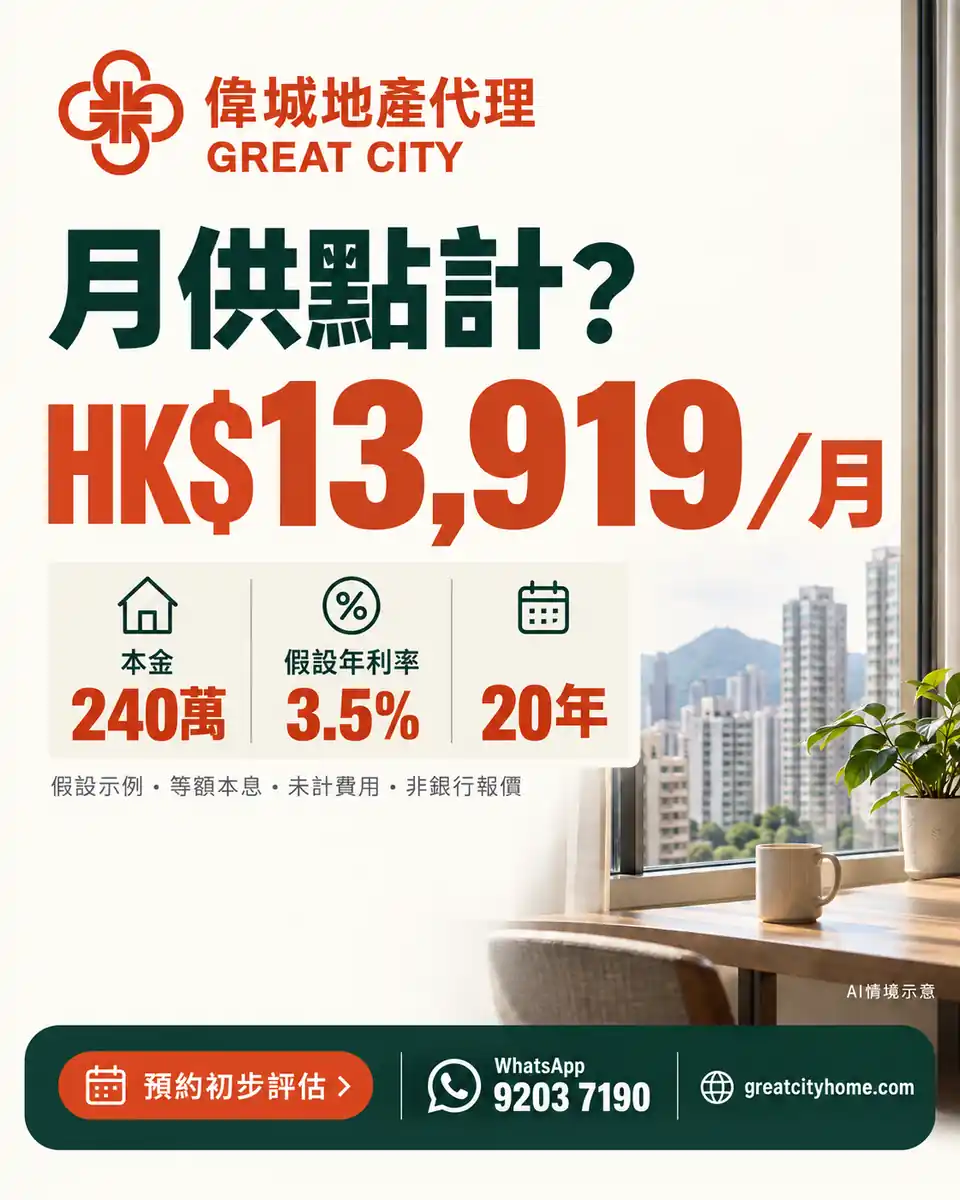
How is a monthly payment calculated?
Principal, the assumed rate and term all affect the monthly payment; total interest and fees complete the comparison. Current poster artwork is in Traditional Chinese.
Assumptions: HK$2,400,000 principal, fixed 3.5% annual rate and equal monthly principal-and-interest payments; only the 20/25-year term changes. Fees, incentives, penalties and rate changes are excluded. This is not a lender quotation.
Explore this planning page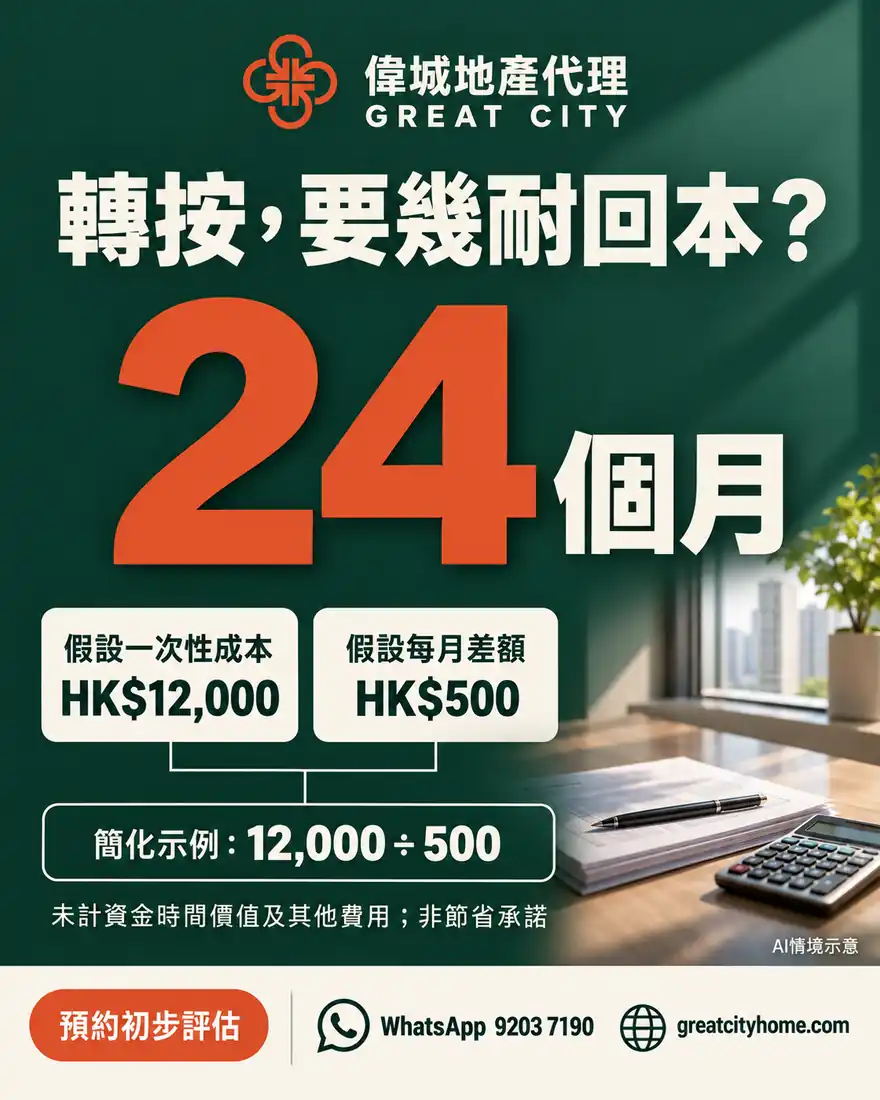
12,000 ÷ 500 = 24 months
A simple break-even is a screening tool and does not prove an option is cheaper. Current poster artwork is in Traditional Chinese.
Simple assumptions: HK$12,000 one-off cost, HK$500 monthly difference, and the same principal and term. Time value of money and other fees are excluded, so this cannot establish that an option is truly cheaper.
Explore this planning page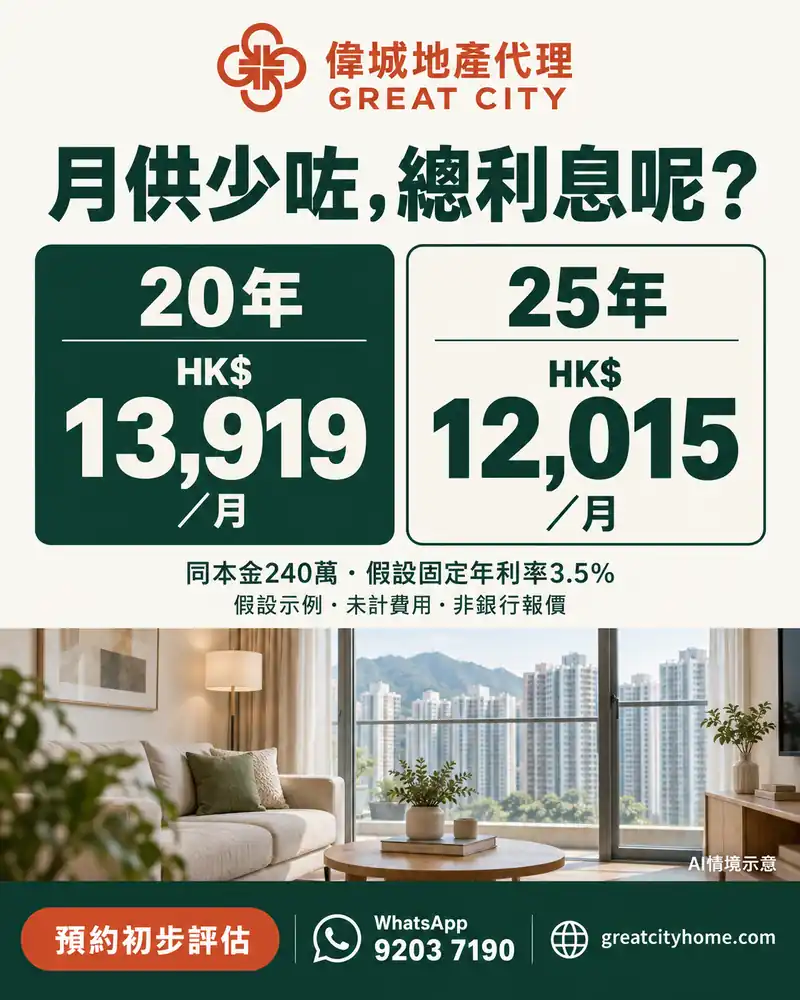
20 years vs 25 years
With the same principal and assumed rate, a longer term can lower the payment and raise total interest. Current poster artwork is in Traditional Chinese.
Assumptions: HK$2,400,000 principal, fixed 3.5% annual rate and equal monthly principal-and-interest payments; only the 20/25-year term changes. Fees, incentives, penalties and rate changes are excluded. This is not a lender quotation.
Explore this planning page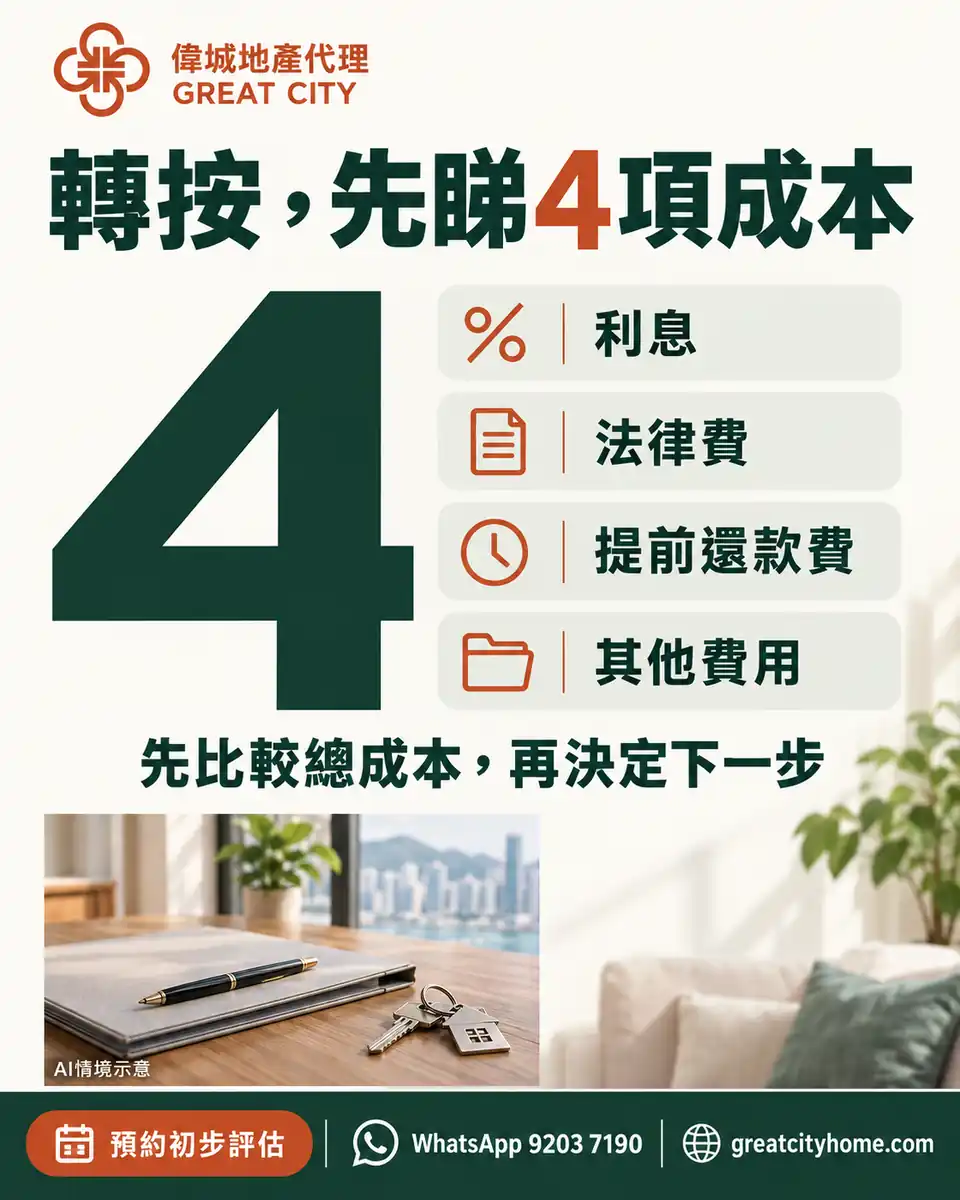
Four cost groups before refinancing
Compare interest, legal fees, early-repayment charges and other costs in the same table. Current poster artwork is in Traditional Chinese.
Explore this planning page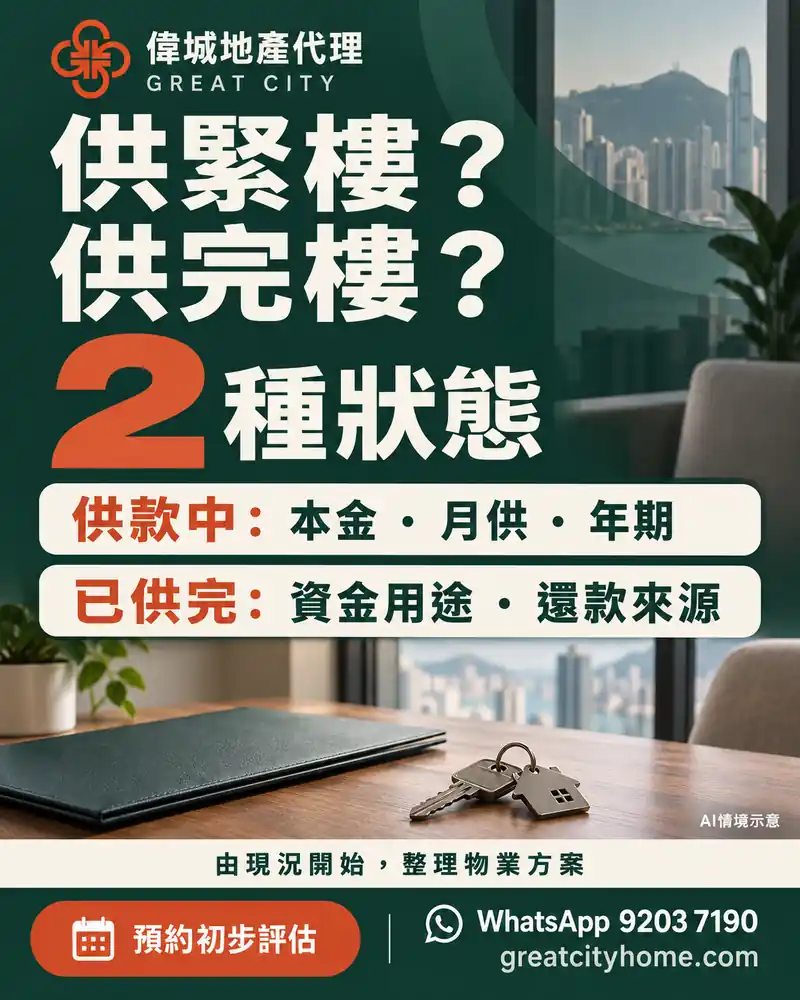
Still paying, or mortgage repaid?
For either property status, first organise valuation, existing debt, intended use and responsibilities before deciding where to make a formal enquiry. Current poster artwork is in Traditional Chinese.
Explore this planning page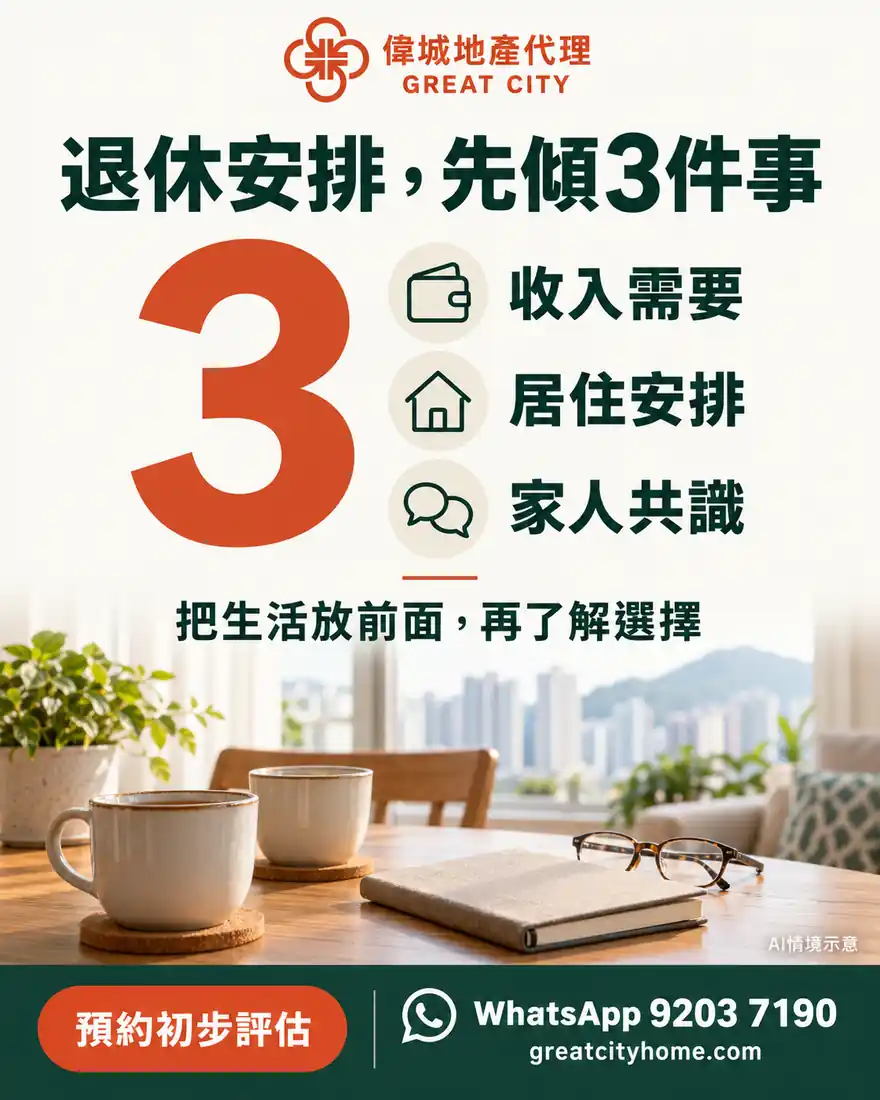
Three retirement questions together
Discuss the income gap, housing stability and family arrangements before deciding. Current poster artwork is in Traditional Chinese.
Explore this planning pageCompare other planning directions
MORTGAGE PLANNING
Mortgage planning: compare payment, term and switching costs in one view
Organise the existing mortgage and compare monthly payment, total interest, remaining term and one-off costs before requesting formal information.
Explore this directionPROPERTY FUNDING
Property funding: define the use, repayment source and downside first
Start with the purpose and repayment source, then organise valuation, existing debt, new interest and costs into an initial comparison framework.
Explore this directionRETIREMENT PLANNING
Retirement property planning: discuss income, home and family together
Use one retirement budget to compare staying, renting, selling or exploring a reverse mortgage, including housing, redemption, debt and family questions.
Explore this directionRelated owner guides
The related in-depth guides are currently available in Traditional Chinese and include detailed question lists and official sources.
Want to organise your own figures in one view?
For a first enquiry, provide only a broad property district, valuation and loan range, and your main goal. Do not send an identity document, full property address or bank records.
Book a one-to-one initial property review